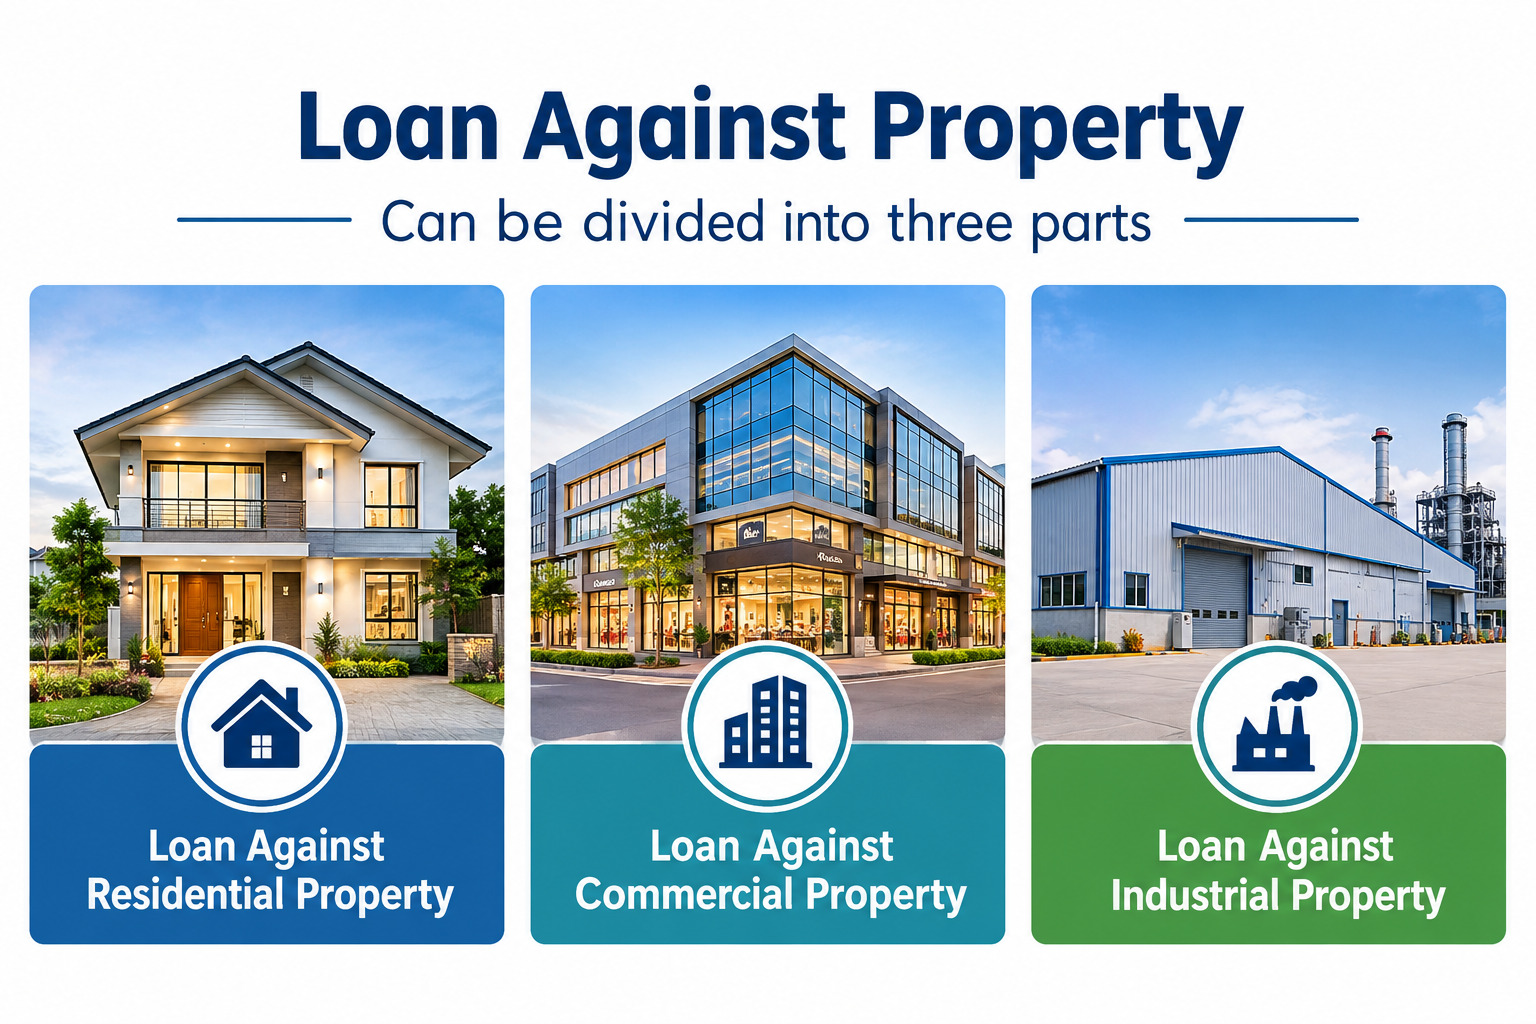
A loan against property secured by real estate is a secured loan that allows homeowners to obtain funds by mortgaging their primary residence with a bank or financial institution.
A key difference between a conventional mortgage and a mortgage secured by real estate lies in the loan-to-value (LTV) ratio. Many conventional mortgages, depending on the property and applicable lending criteria, offer financing that covers a higher percentage of the property’s appraised value. In comparison, the amount of a mortgage secured by real estate typically ranges from 60% to 70% of the market value determined by the lender, although this percentage may vary.
A loan against property can be advantageous for homeowners who need to access significant sums of money without selling their property. This type of loan typically offers a structured repayment plan and can be used for various permitted purposes, subject to the lender’s terms and conditions.
Choosing the right lender is crucial, as interest rates, loan-to-value (LTV) ratios, processing requirements, valuation methods, loan terms, required documentation, and other conditions can vary significantly. Professional advice can help homeowners clarify their situation, compare available loan options, and navigate the loan process smoothly.